KEY TAKEAWAYS
- BIN and IIN are the same digits; IIN is the ISO term.
- Modern IINs can be 8 digits, not 6.
- Store at least 8 digits for correct routing.
- Neither tells you if the account is active.
- History retains the BIN and IIN distinction results for the retention window, then purges them.
- Every the BIN and IIN distinction result class should map to a defined workflow action.
Plenty of arguments about BIN vs IIN are really arguments about naming — with one substantive difference: length.
One digit range, two names
“BIN” (Bank Identification Number) was the original industry term; ISO/IEC 7812 formalised “IIN” (Issuer Identification Number) because non-bank issuers exist. The digits are the same.
Six or eight digits
Historically the IIN was six digits. As ranges exhausted, ISO expanded it to eight digits; card networks now publish 8-digit ranges for many products. Systems that hard-code six digits misclassify modern cards.
Practical impact
Truncate or pad at your peril: routing, fee calculations and issuer analytics can all be wrong if you assume six digits. Store at least the first eight.
Verification is unaffected
Whatever the prefix, account status still requires an issuer round-trip — the BIN tells you the issuer, not the account state.
BIN and IIN describe the same leading digits of a card number; the difference is emphasis, not substance. Bank Identification Number is the payments-industry term that grew up around card routing; Issuer Identification Number is the standards-body term that also covers non-bank issuers. Both resolve to issuer, network, and often program and country.
What neither resolves is account status. The prefix identifies who issued the number and what kind of card it is — reference data. Whether the account is open is a live-check question. Keeping those two layers separate is the whole point of the BIN tools on this site.
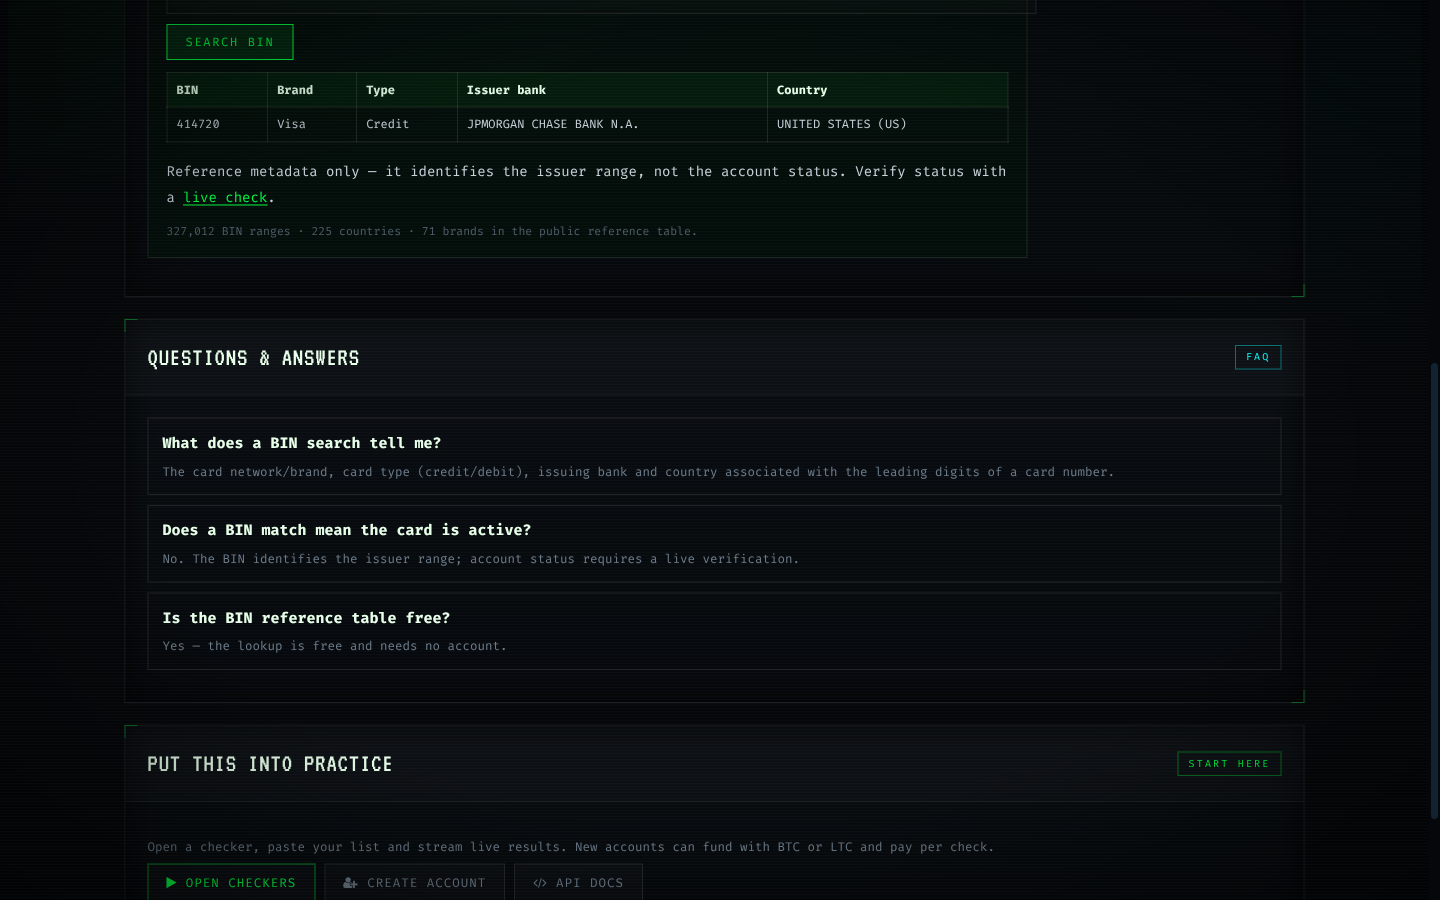
Reference lookups in the BIN and IIN distinction
Analysts use BIN distributions to spot shifts in a portfolio long before individual results would show them. BIN metadata complements verification rather than replacing it: reference first, status second. Six digits usually identify the institution; eight add the program or product level on many ranges. Because BIN data is public reference material, it is safe to cache, but it should be re-validated periodically. Holding that line is what makes the BIN and IIN distinction reliable over time.
Issuer reference data for the BIN and IIN distinction
BIN metadata complements verification rather than replacing it: reference first, status second. Analysts use BIN distributions to spot shifts in a portfolio long before individual results would show them. Segmenting by BIN is useful for routing, risk rules and analytics — the places where issuer identity changes behavior. The public BIN endpoint serves the same reference data programmatically, read-only and without card data. It is a small rule that changes how the BIN and IIN distinction behaves at scale.
Running the BIN and IIN distinction well: the operating steps
When results look wrong, diagnose in order: input format, route, provider health, and only then the cards themselves. Decide how each outcome is handled before the run starts; a triage plan written after the results arrive is usually just a spreadsheet. Treat every large list as two lists: the part that classifies on the first pass, and the remainder that needs a decision about how hard to chase. Keep a small balance buffer so an interrupted run never leaves a half-classified list and the temptation to re-check everything. Write it down; the BIN and IIN distinction workflows live and die on small consistencies.
Interpreting outcomes in the BIN and IIN distinction
Two metrics describe any run: how many cards classify, and how long the pass takes. Everything else is commentary. When a result contradicts other evidence, re-check once after a reasonable interval rather than assuming the checker is wrong. The four result classes are a decision matrix, not a score: live proceeds, dead recovers, unknown gets one careful retry, error returns to the queue. A result is only as fresh as its timestamp. High-value decisions should use checks that ran close to the moment of the decision. That distinction is what keeps the BIN and IIN distinction decisions clean.
Boundaries of the BIN and IIN distinction
The platform does not trade card data, and nothing in the system is designed to bypass a cardholder's consent. Verification is a signal, not a guarantee: a live result does not promise that a later charge will be approved. Check only cards you own or are authorised to process; verification is not a shortcut around cardholder authorization. In the BIN and IIN distinction work, that is the difference between a signal and a guess.
Free tools that support the BIN and IIN distinction
IBAN validation follows country-specific rules and verifies the checksum, covering the payout side of card operations. The test card generator produces checksum-valid numbers for development, and they are never chargeable by design. The CSV cleaner normalises separators and removes duplicates, which is the cheapest way to protect a large run. The habit costs nothing and removes a recurring class of mistakes.
- Luhn validator
- IIN lookup
- bulk checking guide
- Bin Lookup Explained
- Card Issuer Vs Acquirer
- Card Verification Glossary
Running the BIN and IIN distinction as a process
Budget verification against the cost of failure, not against zero; the comparison is what makes spend defensible. Schedule recurring checks ahead of the decisions they inform, not after them. Keep one primary gateway and one fallback, and switch on evidence — error spikes and classified-rate drops — rather than on price alone. Keep the API key server-side and regenerable; a leaked key is a billing incident as much as a security one. The habit costs nothing and removes a recurring class of mistakes.
Common mistakes around the BIN and IIN distinction
Defining result handling after the run in the BIN and IIN distinction produces spreadsheets instead of decisions. Storing card data beyond the needs of the BIN and IIN distinction creates risk without adding value. Comparing the BIN and IIN distinction routes on list price instead of classified rate hides the real economics.
- Increasing parallelism past the provider ceiling in the BIN and IIN distinction converts capacity into timeouts.
- Storing card data beyond the needs of the BIN and IIN distinction creates risk without adding value.
- Using BIN reference data as account status in the BIN and IIN distinction confuses two different questions and produces confident, wrong decisions.
- Retrying a dead card during the BIN and IIN distinction spends balance for an answer that will not change within the run.
What the BIN and IIN distinction cannot promise
Operators remain responsible for the legal basis on which they hold and process card data. A check does not move money, does not create a charge and does not touch the cardholder's credit file. Results describe the account, never the person; they should inform routing and risk decisions, not identity decisions. Write it down; the BIN and IIN distinction workflows live and die on small consistencies.