KEY TAKEAWAYS
- Status checks do not charge or hold the card.
- Some alternative methods place a temporary hold that is released.
- Billing happens on your platform balance, not the card.
- Authorisation is separate and only for taking payment.
- History retains non-charged card checking results for the retention window, then purges them.
- Every non-charged card checking result class should map to a defined workflow action.
The common fear — “will checking the card charge it?” — has a precise answer, and it depends on the method.
Status checks
Modern verification uses account-status inquiries that confirm live/dead without creating a charge. The cardholder sees nothing.
When holds can appear
Some methods place a small temporary authorisation, which appears as pending and is released. This is not a charge, but it can concern cardholders.
What we use
Our checking is designed around non-financial verification: classified results are billed against your platform balance, never the cardholder’s.
When you actually need a charge
Only when you are taking payment. Verification answers status; authorisation and capture move money.
Next step
A verification request is built to answer a question, not to move money: it produces a status result and no settlement. That is the entire design difference between checking a card and charging it. The platform bills per classified result from your prepaid balance — a platform charge, not a card charge — and nothing reaches the cardholder's account.
Where this matters operationally is authorization holds. Some routes generate an authorization-shaped event that can place a temporary hold; the platform's checker flows are documented so you know which behaviors to expect. If a hold concern appears in your workflow, use a validation route that avoids capture entirely.
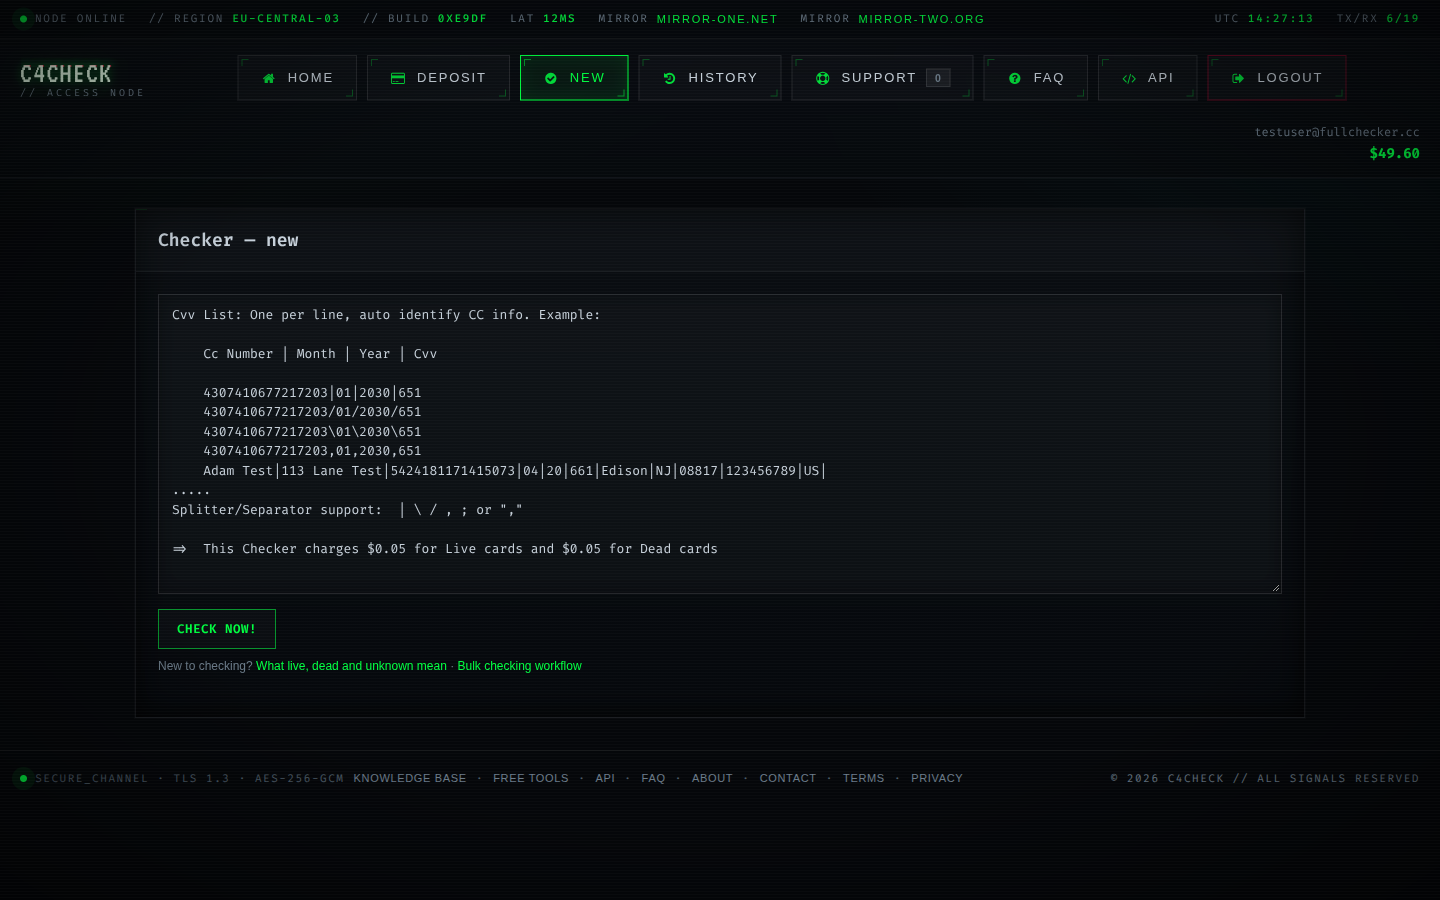
Key points about non-charged card checking
- Verification does not capture funds; it asks for status and records the answer.
- Billing is per classified result on your platform balance, never on the checked card.
- Know your route: authorization-shaped requests are not charges, but they are visible to issuers.
- Test the behavior on a pilot card you own before scaling to a customer list.
Reading non-charged card checking results honestly
When a result contradicts other evidence, re-check once after a reasonable interval rather than assuming the checker is wrong. Dead results are conclusive for the moment and should never be re-checked in the same run; retries on dead cards spend balance for identical answers. A live answer is evidence about the account, not a guarantee about a specific future transaction; issuer rules can change between the check and the charge. Conflating outcomes is the most expensive habit in this area — an error treated as a dead card discards real inventory, and an unknown treated as live inflates confidence. Holding that line is what makes non-charged card checking reliable over time.
Non-charged card checking in practice: a repeatable path
When results look wrong, diagnose in order: input format, route, provider health, and only then the cards themselves. Deduplicate before submitting: the same card in a list twice is billed twice if both copies classify. Treat every large list as two lists: the part that classifies on the first pass, and the remainder that needs a decision about how hard to chase. Keep a small balance buffer so an interrupted run never leaves a half-classified list and the temptation to re-check everything. It sounds obvious until a real run tests it.
Limits and responsible use of non-charged card checking
A check does not move money, does not create a charge and does not touch the cardholder's credit file. When a proposed use cannot be explained to a compliance reviewer in one sentence, it is probably not a fit. Operators remain responsible for the legal basis on which they hold and process card data. Remember it the next time non-charged card checking produces an ambiguous answer.
Non-charged card checking: from request to result
Unknown means no definitive answer was received — often an issuer challenge or soft decline — so the card remains unclassified and deserves at most one fallback pass. Live means the issuer answered and the account is active and chargeable at that moment; it is strong evidence, not a promise about a future charge. A check sends an authorization-shaped request through a provider to the issuer and classifies the reply into one of four states: live, dead, unknown or error. Behind the scenes, every check follows the same chain: your input, the gateway format, the provider connection, the issuer response and the classification you see. That distinction is what keeps non-charged card checking decisions clean.
Non-charged card checking in numbers
Aggregate numbers describe populations, not individual cards. Use them to size timeouts and retry budgets, never to judge one account. When the classified rate moves, the cause is usually a route or provider change rather than the underlying cards. Latency percentiles matter more than averages: the p90 and p99 tell you what a slow run actually feels like. The reference BIN table covers hundreds of thousands of issuer ranges, and it is deliberately separate from account-status data: one describes issuers, the other describes cards. That distinction is what keeps non-charged card checking decisions clean.
Running non-charged card checking as a process
Keep the API key server-side and regenerable; a leaked key is a billing incident as much as a security one. Alert on classified-rate drops, not just on errors; silent degradation is the expensive kind. Track cost per classified card rather than cost per request; it is the only metric that reflects retries and unknown rates. Keep one primary gateway and one fallback, and switch on evidence — error spikes and classified-rate drops — rather than on price alone. It is a small rule that changes how non-charged card checking behaves at scale.
Pitfalls that cost money in non-charged card checking
Comparing non-charged card checking routes on list price instead of classified rate hides the real economics. Retrying a dead card during non-charged card checking spends balance for an answer that will not change within the run. Validating after the paid non-charged card checking request, rather than before, doubles the cost of bad input.
- Increasing parallelism past the provider ceiling in non-charged card checking converts capacity into timeouts.
- Storing card data beyond the needs of non-charged card checking creates risk without adding value.
- Treating a non-charged card checking snapshot as permanent truth overstates what verification can promise.
- Ignoring the p90 latency of non-charged card checking leads to timeouts that look like provider faults.